Showing posts with label Investing. Show all posts
Showing posts with label Investing. Show all posts
Friday, 30 June 2017

Saturday, 3 June 2017
97% Annual Returns : My Learning and Practices
I started investing into equity markets around a decade back with the guidance of my friend who was already invested in Mutual Funds for a year now. I started with below framework
- Tax Saving Schemes so as to fulfill my Section 80(C) quota
- Six different Fund houses of Indian, Foreign, Private and Public Shareholding
- Systematic Investment Plans of equal amount across 6 different plans
That was my approach of implementing different investment strategies and tools like diversification, cost averaging and tax planning which I could grasp through regular reading of investment and portfolio related articles.
Lot many experiences have got collated in my life since then, in both professional and personal life. Professionally I learnt Wealth Management practices of an American Banking giant while working with Infosys, had my Masters in Finance from IIT Delhi, worked as a Senior Wealth Manager with one of the biggest wealth management player of India and finally shifted to Dubai as a Wealth Manager. On personal front, I got married , faced a huge family medical exigency, bought my first flat and became a father. All of these experiences taught me a lot about personal finances and portfolio management.
Both of these professional and personal events made my own portfolio very unpredictable and short term. Just when I will feel that my investment approach is settling in I will either face a job change or a pressing personal issue. But one thing that always remained constant was my passion for investments. Thanks to the above discussed situations, my portfolio had become very haphazard and heterogeneous, lacking a common approach or set of principals.
So sometime in last phase of last year, I decided to implement in my own portfolio what I always advise to my clients as a Wealth Manager - Proper Asset Allocation based on Relevant Risk Profiling.
Below is a snapshot of my portfolio sometime in Sep'16.
| Scheme Name | Latest Value |
| Birla SL Dynamic Bond -RP (G) | 90016 |
| Birla SL Top 100 - Direct (G) | 33557 |
| BNP Paribas Long Term Equity (D) | 6018 |
| Franklin (I) Bluechip - Direct (G) | 27799 |
| Franklin (I) Prima - Direct (G) | 18865 |
| Franklin (I) Smaller Co -Direct (G) | 7280 |
| Franklin (I) Tax Shield -Direct (G) | 8229 |
| Franklin High Growth Co -Direct | 32949 |
| Franklin India Tax Shield (D) | 6329 |
| ICICI Pru Flexi Income (G) | 106071 |
| ICICI Pru Focused. Blue -Direct (G) | 27769 |
| ICICI Pru Infrastructure-Direct (G) | 9630 |
| ICICI Pru Long Term Equity | 5827 |
| ICICI Pru Long Term Equity | 26134 |
| ICICI Pru Top 100 Fund - Direct (G) | 16484 |
| ICICI Pru Value Discovery - DP (G) | 11482 |
| Kotak Tax Saver - Regular (D) | 23632 |
| L&T Tax Advantage (D) | 17159 |
| L&T Tax Advantage -Direct (G) | 6149 |
| Reliance Small Cap - Direct (G) | 14928 |
| Reliance Tax Saver(ELSS)-Direct | 13687 |
| SBI Magnum Midcap Fund - Direct | 6347 |
| SBI Magnum Tax Gain - Direct (G) | 27171 |
| SBI Magnum Tax Gain (D) | 4293 |
| SBI Pharma Fund - Direct (G) | 37948 |
A total of 22 schemes haphazardly across asset classes, sectors and market cap. From there on my portfolio now looks like below as on date.


A much leaner and planned portfolio spread across MFs and Stocks. But as they say, more so in the world of Wealth Management, devil lies in details. While MFs gave an annual return of 37% (compounded) , corresponding figure for stocks is humongous 97%.
So what was the difference that brought this huge difference in the returns. Click on 97% Annual Returns : Implementation to learn "How I did it". Click on 97% Annual Returns : Mutual Funds Selection - Statistical Analysis beyond Historical Returns to learn which ratios you need to check to select MF.
Sunday, 10 January 2016
Year Review 2015
As 2015 comes to a dawn let’s do a quick analysis over how this year was in terms of investment and taxation. We will try to list all the big changes in taxation and a brief summary on how asset classes performed during this year. Lets start with changes in income tax rules
- Govt declared Rs 50,000 additional deduction under section 80CCD. So now you can save up to 50,000 Rs in NPS and claim tax benefit on this income.
- Govt doubled transport allowance amount to Rs 1600 Per month from earlier 800 Per month
There were several other minor changes in Tax codes but those were minor ones.

Now coming to various asset class and their performance in past year
Equities: 2015 was supposed to be one big year for equities after euphoric 2014 when SENSEX returns were massive 40%. 2015 was supposed to be an year when corporate earnings will pick up after somber of 2 years, but nothing like that happened actually and equities suffered. This year Sensex and Nifty started year at 27,900 and 8,400 levels and grew 5% in Jan to levels of 29,500 and 8900 respectively before bears became dominant and remain rangebound for whole year. Both the indexes are ending the year down about 6-7%. There were few bright spots in between large disappointments with midcaps giving positive returns of about 6-7%. Overall 2015 have been a disappointing year as far as Indian equities are concerned
Debt: As RBI reduced interest rates debt instrument yield came down and hence prices increased. Overall return of 8%-8.5% were best return available during the year as equities faltered and Gold, reality etc failed to pick up.
Gold: Gold (and all other commodities) remained depressed during 2015. It means Gold have been depressed since last 3 years and there is no revival in sight. But Gold saw some action in terms of some new and very exciting schemes from Govt. More details here.
Real Estate: Real Estate too remained depressed in 2015 with some minor exception. It have also been a 3-4 year phase of consolidation and full scale revival will still take time. Though as credible data is unavailable making sweeping recommendation about this market is difficult but some money have been made in certain pockets but overall market have been subdued.
Overall 2015 was not that good year as far as returns are concerned but it provided a good consolidation which will yield to better results in years ahead
Monday, 22 June 2015
Equity Mutual Funds - An Orientation
Watching “ Pursuit of Happyness “ on Father’s Day is bound to bring all the memories of all the sacrifices that your father made in order to ensure best future for you. But to me in addition to that , it has a very strong but somewhat hidden lesson - One need to challenge his comfort zone/s in life to achieve his full potential. Beyond all the arguments cited by a large section of people against Mutual Fund, deep down is inertia, inertia not to explore something beyond their comfort or lets say awareness zone.
So lets make a beginning and try to understand what Mutual Funds means and their types.
A Mutual Fund in the crudest form has chiefly three components -
- Retail Investor - Like me and you , who contribute money into a common corpus.
- Mutual Fund Company - Is responsible for proper management and upkeep of the corpus. Hires a fund manager and is responsible for the operational , marketing , legal and other issues pertaining to the fund.
- Fund Manager - who invests money on “behalf of the Retail Investors” as per the objective and strategy of the fund.

Mutual Funds at the most basic level are of two types, based on the kind of assets that they invest in -
- Equity Mutual Fund
- Debt Mutual Fund. Click Here to learn about them. If you want to learn how Debt Mutual funds minimise your tax outgo, Click Here .
Equity Mutual Funds invests in equity i.e. shares and related instruments. Here is a brief go through the different types of Mutual Funds -
- Large Cap Funds - They typically invests in the companies that occupies the top positions on the stock exchange as per cumulative value of all their shares being traded (known as Market Capitalisation).These companies are also known as Bluechip Companies. Common examples will be - Hindustan Unilever, Larsen & Turbo etc. Being market leaders of their respective domain , they command high value in stock exchange and are also the least volatile in their valuations. Hence Large Cap Mutual Funds are supposed to be the safest category among all Equity Mutual Fund categories.
- Mid Cap Funds - They occupy the middle order in the Market Capitalisation deck. They are more volatile than Large Cap Funds but also have more potential of growth.
- Small Cap Funds - They invest in the novice companies who have got low market share or low market penetration or who operate in a product or service category which have very low market potential. Being very small in revenue and profits , they have a high potential for growth in their valuations. But they also are quite risky as such companies can neither be analysed properly nor have strong promoters.
- Diversified / Multi Cap Fund - They invest across companies irrespective of their Market Capitalisation. The idea is to provide “Diversification” and hence minimise volatility with a higher return than Large Cap Funds.
- Sector/Thematic Fund - They invest in companies of a particular sector and hence are highly correlated with the performance of that sector.
- Tax Saving Fund - They are alternate of traditional Tax Saving instruments like PPF, NSC etc. having lock in period of three years. Click Here to learn how they minimise your tax obligations.
- Equity Oriented Hybrid Funds - They have major part but not all of the investments into equity. They also invest in asset class like Debt etc.
So now that you have learnt quite a bit about Equity Mutual funds, why don't you go out and put some money into them. Because doing is the best tool of learning.
In case you would like to follow our future posts and go through our past posts as well, do remember to Like our Facebook Page . Do remember to share you feedback and brickbats through email on healthynivesh@gmail.com or in the comments box. Wish you make Healthy Nivesh.
Monday, 13 April 2015
Debt Funds - The Tax Warrior against FDs
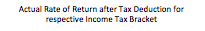
Fixed Deposits have long been associated with assured returns for most of our contemporary and previous generation population. A “tension free” return of 8-10% has meant the holistic investment planning for many of us. But this “tension free” return comes at a huge cost in the form of ensuing taxability. Below is an illustration how Taxes eat into our FD returns.
Annual Interest on FD
|
10%
|
20%
|
30%
| |
8%
|
7.2%
|
6.4%
|
5.6%
| |
9%
|
8.1%
|
7.2%
|
6.3%
| |
10%
|
9.0%
|
8.0%
|
7.0%
|
* If you feel difference of 1-2% is nothing you might want to know about power of compounding
So as the above illustration shows, net return of FDs keeps on decreasing with rise in applicable tax bracket, making the ‘safe’ return of FDs even lower. There are two more points to take note of as far as taxation of FDs is concerned:
1. One has to declare interest earned on FDs every financial year irrespective of investment or maturity date of the FD. E.g. you make an FD in Dec’12 for three year duration, so you are supposed to declare interest accumulated in the financial year 12-13, 13-14 and 14-15 separately in the respective financial year income tax return.
2. Contrary to popular perception there is no tax free interest on FDs. Some people think that interest earned upto 10,000 in a financial year is tax free. But reality is that limit is for saving account interest only, not FDs.
So is there is any alternate which is as safe and more tax efficient ?
Yes there is and its known as Debt Funds.

Before exploring how Debt funds are more tax efficient than FDs, lets first explore what Debt funds are.
Before exploring how Debt funds are more tax efficient than FDs, lets first explore what Debt funds are.
Banks offer FDs for raising money, in the same manner companies offer different Debt instruments like Commercial Papers, Debentures, etc to raise money for their capital needs. Following is the nature of these instruments –
- Rated by independent rating agencies like CRISIL etc for their creditworthiness
- Intermittent in nature – Unlike bank FDs they are not available for subscription continuously. Companies offer them only when they need capital for some specific or general working capital requirement.
- Rate of Return offered by these instruments depend on the ratings. So higher is the rating, lower is the rate of return
Debt funds function in below manner –
- Mobilise money from retail investors like me and you
- Invest the money thus collected in different debt instruments like the ones defined above, apart from government bonds , money market instruments etc.
- Allocate ’Units’ to investors based on their quantum of investments
- Payback money to investors when they redeem their investments
Now coming to taxation part, Debt funds score over FDs because you can use Inflation to pare down your returns for tax calculation. Instead of going into theory, lets try to understand it by an example -

*Capital Appreciation considered for Tax Calculation
Fixed Deposit = [(D) - (B)]
Debt funds = (D) - [(B) *[(Inflation Index during (D)/Inflation Index during (A)]
Inflation Index = A parameter based on ensuing inflation for respective financial year , declared for every financial year by government.
Redemption = Process of taking out investment
Capital appreciation = Amount considered for calculating tax
Returns After Tax = Returns realized after paying applicable tax
So as we can see from above example, even though a Debt fund’s returns were supposed to be lower than a FD, in reality it gave better returns because of lower taxation.
But above taxation is applicable only if investment is made for more than 3 years, otherwise it remains same as that of FD.
Wait for our next article to learn What are types of Debt funds and how to invest in them.
Inflation Index i.e. Cost of Inflation Index (CII) is as below for different financial years –

You might also like to read about my perspective about Financial Planning. And as always thanks for reading and if you like it shout out :) help your friends by connecting him/her to us via facebook or email : healthynivesh@gmail.com
Sunday, 12 April 2015
Sukanaya Samriddhi Scheme- For the Luxmi of the Family
India is a country of ironies. This phenomenon gets manifested in worst manner possible in our attitude towards our girls. While we worship female form as a manifestation of power (Durga), love (Radha), money (Laxmi), knowledge (Saraswati) and lot more, we also sadly have one of the worst gender ratio - thanks to rampant female foeticide and infanticide.
It is to counter this harsh reality that government has introduced Sukanaya Samriddhi Scheme , which aspires to provide a secure, long term and ASSURED investment option for girl child. Lets have a look at the details.

Eligibility
Account can be opened subject to following conditions -
- In the name of girl child up to 10 years of age
- Maximum of one account per girl child
- Maximum of two accounts by one set of parents – third account can be opened provided two the girls children are twins or all three are born together.
Account Opening
Following documents are required -
- Birth Certificate of girl child
- ID and Address proof of the guardian of the child-who will operate the account on her behalf till she attains the age of 10 years, after which both guardian and girl child can operate the same
- Account can be opened either in a post-office or PSU bank
- Account can be transferred all over India in case account holders shifts her base
Rules
- Minimum contribution of Rs. 1000/- in a financial year
- A penalty of Rs. 50 if minimum contribution not made in a year
- Maximum contribution of 1.5 lakhs in a year
- Deposits can be made only for a period of 14 years from the date of account opening
- No deposits shall be accepted from the 15th year of account opening
Withdrawal
- Permitted upto 50% of total amount when girl child turns 18.
- Fully withdrawable when girl turns 21 or when she gets married, if she get married before turning 21.
- After girl turns 21, account can be closed, otherwise it will continue getting interest on the accumulated amount, but no more deposit will be accepted.
Interest and Taxation
- For the current financial year, government has declared 9.1% as annual interest rate
- Full amount deposited under the scheme is tax exempted under Section 80(C)
- All the interest income on the deposit is also tax free
- The amount withdrawn from the account is also tax free
To summarise the scheme provides a very lucrative option for parents of girl child, but as always this scheme has to be analysed for the suitability in a holistic manner instead of temptation of promised high returns. Against the pros of High assured rate of return and Tax benefit , cons score in the form of illiquidity and hardship of facing PSU banks , which are most of times not willing to help even for smallest of the work, leave alone account opening.
Ever wondered why for some people PPF and Sukanya Samriddhi are best investment while for others it is Equities- Risk is the answer. Know your risk here. We do individual investment advice as well. Write to us at healthynivesh@gmail.com. For weekly investment advice like us on facebook. We promise we won’t spam :)
Subscribe to:
Posts (Atom)